How to Buy a Home on a Short PCS Timeline in Peyton, Colorado
Military families can buy a home with a short timeline by organizing financing immediately, setting clear priorities, and assigning deadlines to every step from touring through closing. A PCS purchase can move quickly without becoming careless when the household, lender, and agent follow one shared plan.
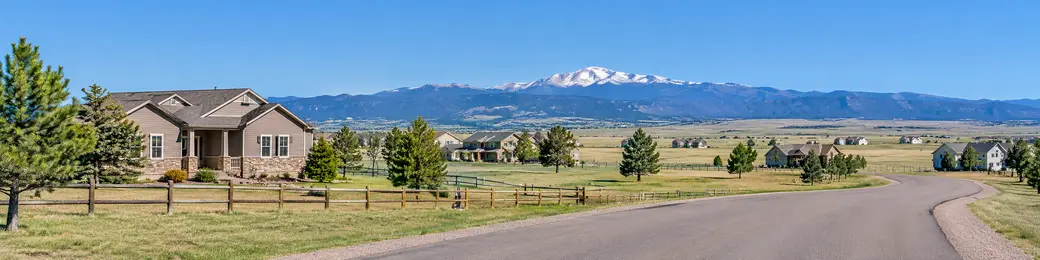
For a move to Peyton, Colorado, start by working backward from the report date or arrival date. Decide when you need to be under contract, when closing needs to occur, and where the family will stay if possession does not line up perfectly. Peyton is an unincorporated community in El Paso County, so each property deserves an address-specific review of its commute, utilities, road access, service coverage, and everyday fit.
A short timeline does not mean every decision must happen in one day. It means the right decisions should happen in the right order: financing first, then search criteria, tours, offer terms, contract deadlines, and closing logistics.
Get Preapproved Right Away to Buy a Home With a Short Timeline
A complete preapproval gives military buyers a usable price range and the confidence to act when the right property appears. It is more helpful than a quick estimate because it begins the lender's review of the information needed for the loan process.
Create one secure digital folder for recent leave and earnings statements, bank statements, identification, documentation for other income or assets, and PCS orders. Eligible service members and veterans can also begin collecting VA loan eligibility information through the Department of Veterans Affairs' VA home loans program.
Choose a lender who understands military income, travel schedules, secure document delivery, and the realities of an approaching report date. Ask how the team handles changing orders, a spouse who is traveling, and requests that need a same-day response. The goal is not simply to receive a letter. It is to establish a communication routine that keeps the loan moving while the household manages a relocation.
Set a payment range that accounts for taxes, insurance, utilities, maintenance, commuting, and any applicable community fees. Comparing several scenarios with a mortgage calculator can help buyers stay focused on a sustainable monthly payment rather than only the list price.
Narrow Your Must-Haves Quickly
A short search works best when the household agrees on a few true nonnegotiables before viewing homes. Start with daily-life requirements, such as bedroom count, location, workspace, storage, pet needs, lot preferences, and the routes that will shape the family's routine.
Separate those needs from features that can be changed later. Paint colors, fixtures, and some cosmetic updates may be manageable after closing. Location, layout, condition, and monthly affordability are much more difficult to change once the purchase is complete.
Limit the active search to two or three target areas rather than attempting to compare every available option at once. For homes with a Peyton mailing address, a location label alone cannot answer whether a property suits your routine. Review the exact address, travel routes, nearby services, road conditions, and utility setup for each home. The Peyton area home search can provide a focused starting point for homes that fit the family's criteria, and the Peyton market page adds local context on recent sales.
It also helps to consider flexibility beyond this PCS move. A practical layout, manageable upkeep, and broad appeal can make future decisions easier if another assignment changes the household's plans. That is not a reason to buy solely for a future move. It is a reason to avoid compromises that create unnecessary pressure later.
Use Remote Tools to Buy a Home With a Short Timeline
Remote tools can support a careful home search when an in-person trip is not practical before the report date. Listing photos and virtual tours are useful starting points, but live video walkthroughs allow buyers to ask questions and see details that polished images may not show. Neighborhood walkthrough videos can add context on the surroundings.
During a video tour, ask the agent to move slowly through room transitions, closets, mechanical areas, exterior spaces, drainage points, and the route into the home. Request views from windows and ask about visible wear, natural light, traffic, neighboring properties, storage, and the overall feel of the lot.
An in-person preview by a trusted local agent adds important context that a screen cannot always provide. The agent can compare the property with the family's stated priorities, flag visible concerns, and explain how the home feels relative to other options. That perspective is especially valuable when buyers are balancing travel, work responsibilities, and a compressed relocation schedule.
Keep every candidate property in a shared list with the price, strengths, concerns, deadlines, and next action. Fast decisions are easier when both spouses are reviewing the same information instead of trying to reconstruct details from messages and memory.
Write a Strong, Clean Offer
A strong offer is complete, realistic, and built around the buyer's real ability to close on schedule. Price matters, but sellers also consider financing readiness, earnest money, requested dates, and whether the offer creates avoidable uncertainty.
Work backward from the report date, travel plan, and lender milestones to propose a closing date that the full transaction team can support. A date that sounds appealing but cannot be met by the lender, title company, or buyers adds risk instead of value. Be clear about meaningful timing constraints so the offer reflects a workable plan.
Keep the offer focused on the terms that matter to your household. Organized financing, prompt communication, and timely document review can help make an offer easier for a seller to evaluate when there are competing choices.
Military families should also decide who can review documents and make time-sensitive decisions if one spouse is training, traveling, or otherwise unavailable. Establishing that decision process before an offer is submitted can prevent delays after a seller responds.
Keep Due Diligence on Schedule
Due diligence stays manageable when key appointments and document reviews are arranged as soon as the contract allows. A short closing period leaves little room to wait on property questions or lender requests.
Schedule the home inspection promptly, then review the findings with your agent and appropriate professionals before contractual deadlines pass. The purpose is not to expect a perfect home. It is to understand the property's condition, identify significant concerns, and make informed decisions while options remain available.
The appraisal process also needs early coordination, particularly for VA-financed purchases. Respond quickly when the lender requests updated documents, explanations of deposits, employment information, or other verification. In many fast transactions, unanswered requests create more delay than the requests themselves.
Set a practical communication routine for the contract period. Check email and phone messages at planned times each day, identify who can respond when one spouse is unavailable, and alert the lender and agent about travel days that may affect turnaround times.
Plan a Remote or Flexible Closing
A remote or flexible closing is possible when the signing plan is confirmed early with the lender and title company. Requirements can vary by document, lender policy, and location, so buyers should not assume every form can be signed electronically.
Raise any deployment, training, travel, or report-date constraint at the beginning of the financing process. Ask which documents require notarization, whether mobile-notary options are available, and whether a properly prepared power of attorney may be appropriate. A power of attorney should be tailored to the transaction and reviewed with qualified legal and title professionals before it is needed.
Before closing, confirm how funds will be delivered, how keys will be released, and who can complete the final walkthrough if the buyers cannot attend. A written closing checklist reduces last-minute uncertainty and makes a remote purchase more predictable.
Have a Backup Plan
A backup housing plan gives military families flexibility when arrival and closing dates do not align exactly. Even well-managed transactions can shift, so temporary lodging should be part of the overall strategy rather than evidence that the plan failed.
Consider short-term rentals, extended-stay lodging, family accommodations, or another arrangement that fits the household's needs. Keep essential documents, medications, school records, pet information, and daily-use items accessible instead of placing them in long-term storage.
Plan for the first week after arrival, too. Decide how transportation, internet service, deliveries, and utilities will be handled if the home is not immediately available. A practical contingency plan gives buyers more confidence to pursue the right property without making a decision based only on the calendar.
For military families buying a home with a short timeline in Peyton, Colorado, speed and care can work together. Organized financing, precise home screening, responsive communication, and a realistic backup plan help protect the household while keeping a PCS move on track.
Talk With a Military Relocation Specialist
Daniel Padilla is a retired U.S. Army Chief Warrant Officer and the founder of The PCS Team, a licensed real estate team operating under Real Broker, LLC. The team specializes in military PCS relocations and VA-related home moves, and its agents hold designations that include Military Relocation Professional (MRP). For military buyers near Peyton working against a report date, that means help with remote searches, video tours and in-person previews on your behalf, offer terms, and flexible closing plans.
To talk through your report date and timeline, call +1 (719) 900-6998, email info@thepcsteam.com, or use the contact page. You can also read more client feedback on the team's public agent profile.
Frequently Asked Questions
How fast can a VA loan close?
A VA loan can close on a compressed schedule when the lender, buyer, title team, and property-related steps stay coordinated. The timeline depends on lender capacity, document readiness, property details, and the terms negotiated in the contract.
Can I buy a house without seeing it in person?
Yes, buyers can purchase a home without an in-person visit when they use live video tours, a trusted local agent, and a detailed review process. Video walkthroughs should cover the home, exterior, lot, storage, visible condition, and surrounding setting.
Should I waive the inspection to speed things up?
Waiving an inspection is generally not recommended because it can leave buyers without important information about the property's condition. Scheduling the inspection quickly and making timely decisions within the contract deadlines is usually the more balanced approach.
What if I arrive before closing?
Temporary lodging can bridge the gap when a household arrives before possession is available. Keeping essentials accessible, arranging short-term accommodations, and confirming a backup plan can make the transition easier while the closing is completed.
Categories
- All Blogs (61)
- Buying A Home (17)
- Colorado Living (28)
- Colorado Springs Real Estate (25)
- Colorado Springs Relocation (25)
- Crossfit (5)
- Divorce (4)
- Gym (5)
- Homebuyer Resources (16)
- Join Real (12)
- Military Orders (17)
- Military PCS Moves (18)
- Military Relocation (18)
- Neighborhood Guides (16)
- PCS Moves (19)
- Real Estate (15)
- selling (3)
Recent Posts
GET MORE INFORMATION