First-Time Home Buying Tips for Military Families
The best first-time home buying tips for military families are to verify VA loan eligibility early, keep the payment below your comfortable limit, and plan for a future PCS before making an offer. Buying a first home while serving is exciting, but it differs from a civilian purchase because orders, travel, and family schedules can change quickly.
Understand Your VA Loan Benefit
A VA-backed loan can allow eligible borrowers to purchase a primary residence with no down payment and no monthly private mortgage insurance. Start by requesting your Certificate of Eligibility, or COE, so a VA-experienced lender can confirm your eligibility and available entitlement before you begin comparing homes.
The VA funding fee is a one-time charge that may apply to a purchase loan. Some borrowers may qualify for an exemption, including certain borrowers receiving service-connected disability compensation. Review the current VA funding fee and closing-cost guidance before choosing a loan structure, since the applicable fee depends on your circumstances and loan details.
A VA loan is often a useful first option for eligible military buyers, but it is still important to compare the full payment, lender terms, cash needed at closing, and how the home fits your PCS plans.
First-Time Home Buying Tips for Military Families: Set a Budget That Fits Military Life
A workable military home budget treats BAH as a planning guide, not as the maximum payment your household can carry. A lender's approval amount is an important starting point, but it may not reflect savings goals, child care, vehicles, travel, family support, or the flexibility needed when orders change.
Begin with dependable household income and list the full monthly cost of ownership. Include principal and interest, property taxes, homeowners insurance, association dues when applicable, utilities, internet, commuting, routine maintenance, and savings for unexpected repairs. For properties in and around Peyton, an unincorporated community in El Paso County, lot size, heating and cooling needs, water arrangements, and drive times can affect the monthly picture just as much as the sale price.
Build your budget around a conservative month rather than a perfect one. Consider what happens if a spouse changes jobs, travel increases, a vehicle needs work, or a move arrives earlier than expected. Leaving room in the budget can make homeownership easier to sustain through those changes.
The Peyton area housing information can help you compare property settings, travel routes, and ownership considerations. Use it as local context, then ask your lender to prepare payment scenarios for the specific homes and loan terms you are considering.
Before touring, decide what monthly payment still lets you save, handle routine upkeep, and maintain a PCS reserve. A payment that feels comfortable on paper should also work when military life becomes less predictable.
Know the Real Costs of Buying
Buying a home requires cash planning beyond the down payment, including earnest money, closing costs, prepaid items, and move-in reserves. Ask for written estimates early so you understand the funds connected to a particular property, loan option, and closing date. For VA purchases, it also helps to know which closing charges a VA buyer can and cannot pay before you start negotiating.
| Category | What to plan for |
|---|---|
| Earnest money | A deposit submitted after an accepted offer that is generally credited toward closing funds when the contract is completed under its terms |
| Closing costs | Lender charges, title services, recording expenses, and other transaction-related fees |
| Prepaid items | Initial homeowners insurance, property taxes, and funds collected for future bills |
| Move-in reserves | Utility deposits, immediate upkeep, furnishings, and an emergency cushion |
Earnest money is not simply an additional fee. Its treatment depends on the contract language, deadlines, and circumstances of the transaction, so keep clear records and understand the terms before sending funds.
Seller concessions may help with certain allowable buyer closing expenses, but they are negotiated as part of the full offer. They are not guaranteed, especially when several buyers are interested in the same property. Consider the purchase price, requested concessions, financing terms, condition, and closing timeline together instead of focusing on one number.
The Consumer Financial Protection Bureau's Loan Estimate explainer describes how estimated cash to close accounts for the down payment, closing costs, deposits already paid, seller credits, and other adjustments. Compare those figures with your available savings and a reserve that remains after move-in.
An affordability calculator can help organize payment scenarios, but your lender's written estimate should guide the final cash plan for your chosen loan and property.
First-Time Home Buying Tips for Military Families: Think About Your Next PCS Now
A first home should work for your household today while preserving practical choices if PCS orders arrive sooner than expected. You cannot control assignment timing or future market conditions, but you can select a property with flexibility in mind.
Start with the day-to-day experience. Consider the routes you expect to drive, driveway access during changing weather, storage, bedroom count, parking, outdoor upkeep, and whether the layout can support another stage of family life. A larger lot or more rural setting can be appealing, but it may also bring additional maintenance, commuting, utility, and long-distance management responsibilities.
For military households considering Peyton, it helps to map your real errands, work travel, and property-maintenance demands before committing. Visit the area at different times when possible, and use a virtual tour as one part of the decision rather than the entire decision. If a visit has to wait, neighborhood walkthrough videos can help you picture the drive and the surroundings before you travel.
For a potential future rental or resale choice, focus on broad usefulness instead of trying to predict a perfect outcome. A home's condition, parking, layout, location, utility needs, and upkeep demands can shape how manageable it is for another household. Review any neighborhood rules, insurance considerations, and the practical challenge of managing a property from another duty station.
The Peyton market page provides local housing context that can support conversations about timing and property type. It cannot predict demand for an individual home, so pair broad market information with a property-specific plan.
Before closing, identify what circumstances might lead you to sell, rent, or retain the home. Keep reserves for the option that becomes realistic, rather than assuming your first plan will always be available.
Build the Right Team
A reliable team helps first-time military buyers stay organized when training, travel, and PCS deadlines compress the timeline. Work with an agent who understands military relocations, a lender familiar with VA-backed financing, and a qualified home inspector who can explain visible conditions and maintenance priorities clearly.
Ask how each professional handles remote communication, document deadlines, virtual tours, and decisions when one spouse is traveling or unavailable. Your lender should explain payment and closing figures in plain language. Your agent can help you evaluate local routes, property upkeep, contract dates, and long-term flexibility.
Common First-Time Mistakes to Avoid
First-time military buyers can reduce avoidable stress by testing each decision against their budget, schedule, and possible PCS timeline.
- Skipping the inspection: A professional inspection helps you understand visible property conditions, maintenance priorities, and questions to address before closing. It cannot predict every future repair, but it provides a clearer starting point for ownership.
- Maxing out the budget: A payment at the top of an approval range can leave too little room for utilities, repairs, travel, savings, or a change in duty station. Choose a price range that preserves financial breathing room.
- Opening new credit before closing: Financing furniture, a vehicle, or another major purchase can change your debt profile before the mortgage is finalized. Keep finances stable and speak with your lender before taking on new credit.
- Ignoring property-specific costs: Taxes, insurance, association dues, commuting, utilities, lot maintenance, and repair needs can vary substantially between properties. Review the full estimated payment and ownership demands for the specific home, not only its list price.
- Buying without a PCS backup plan: Think through what you would realistically do if orders arrive early. A sell-or-rent plan does not need to be perfect, but it should account for reserves, timing, vacancy exposure, and long-distance responsibilities.
- Rushing a remote decision: Virtual tours are useful when paired with detailed questions, documents, photos, and a written priority list. Clear communication can prevent a fast timeline from becoming an avoidable regret.
Buying Your First Home in Peyton?
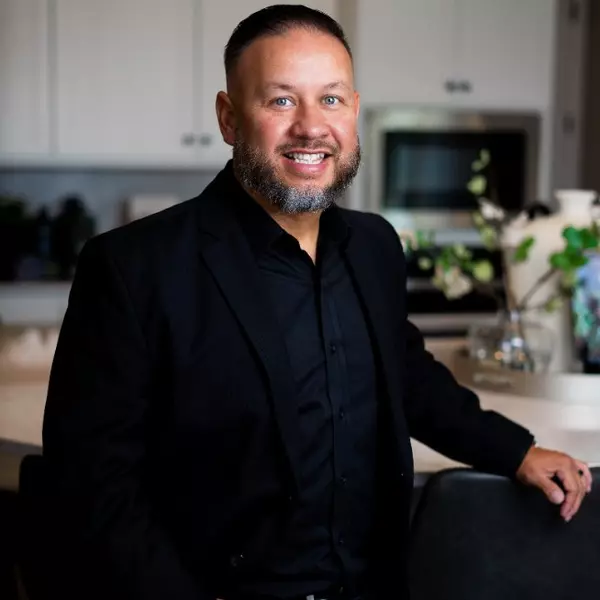
Daniel Padilla is a retired U.S. Army Chief Warrant Officer and the founder of The PCS Team, a licensed real estate team operating under Real Broker, LLC. He works with first-time military buyers in Peyton and the surrounding Pikes Peak region, and the team specializes in military PCS relocations and VA-related home moves while also serving first-time buyers, luxury clients, investors, and sellers. He can help households compare VA loan offers, closing estimates, property upkeep needs, and PCS-friendly home choices, including remote and virtual home tours while you are still at your current duty station.
If orders arrive early and selling becomes the plan, the team also provides home valuations, tailored listing strategies, and a cash offer option for sellers on a tight timeline. Call +1 (719) 900-6998 or email info@thepcsteam.com to talk through your home-buying timeline, budget, and priorities. Past clients share their experiences in the team's client reviews.
FAQ
Is Peyton a good place to live?
Peyton can suit households looking for a lower-density setting, more room to consider property space, and a home layout that supports changing family needs. The right fit depends on the specific location, commute, lot upkeep, utilities, and daily routine. Visit the property and drive your key routes before deciding whether it matches your household's priorities.
Is Peyton expensive?
Peyton housing costs vary by property type, lot characteristics, insurance, utility needs, commute, and financing terms. Rather than relying on a single area-wide cost figure, compare the complete monthly estimate for each home, including taxes, insurance, association dues if applicable, and maintenance reserves. That approach gives military buyers a more useful view of affordability.
What salary do you need in Peyton?
There is no single salary requirement for purchasing a home in Peyton because affordability depends on the purchase price, loan terms, recurring debts, insurance costs, and savings goals. A household should build its price range around dependable income and a payment that leaves room for maintenance, moving expenses, and PCS-related changes. Request several lender scenarios before setting a firm ceiling.
Is a VA loan good for first-time buyers?
For eligible first-time buyers, VA financing can be valuable because it may offer no-down-payment financing and does not require monthly private mortgage insurance. A different loan type may make sense when a buyer is not eligible, wants different terms, or receives a stronger overall option after comparing lender estimates. The best choice is the one that balances payment, closing funds, and long-term plans.
How much should I save before buying?
Plan savings for earnest money, allowable closing costs, prepaid items, moving costs, and an emergency fund that remains after closing. The amount will vary with the loan program, purchase contract, seller concessions, and the home's immediate needs. A lender's Loan Estimate can clarify the expected cash required for a specific purchase.
Can a military spouse buy a home alone?
A military spouse may be able to purchase a home independently, depending on the loan program, income, credit profile, title approach, and VA eligibility. Individual and joint applications can work differently, so a lender should explain qualification options before an offer is written. Household scheduling and document access also deserve early planning.
Should I buy if I might PCS in two years?
A possible two-year PCS timeline does not automatically rule out buying, but it requires a realistic plan for changing circumstances. Consider the home's broad appeal, upkeep needs, potential rental practicality, reserves, and the responsibilities of owning from another duty station. Choose only when the payment and contingency plan remain manageable.
Categories
- All Blogs (53)
- Buying A Home (16)
- Colorado Living (28)
- Colorado Springs Real Estate (25)
- Colorado Springs Relocation (25)
- Crossfit (5)
- Divorce (4)
- Gym (5)
- Homebuyer Resources (16)
- Join Real (12)
- Military Orders (17)
- Military PCS Moves (18)
- Military Relocation (17)
- Neighborhood Guides (16)
- PCS Moves (18)
- Real Estate (15)
- selling (3)
Recent Posts
GET MORE INFORMATION